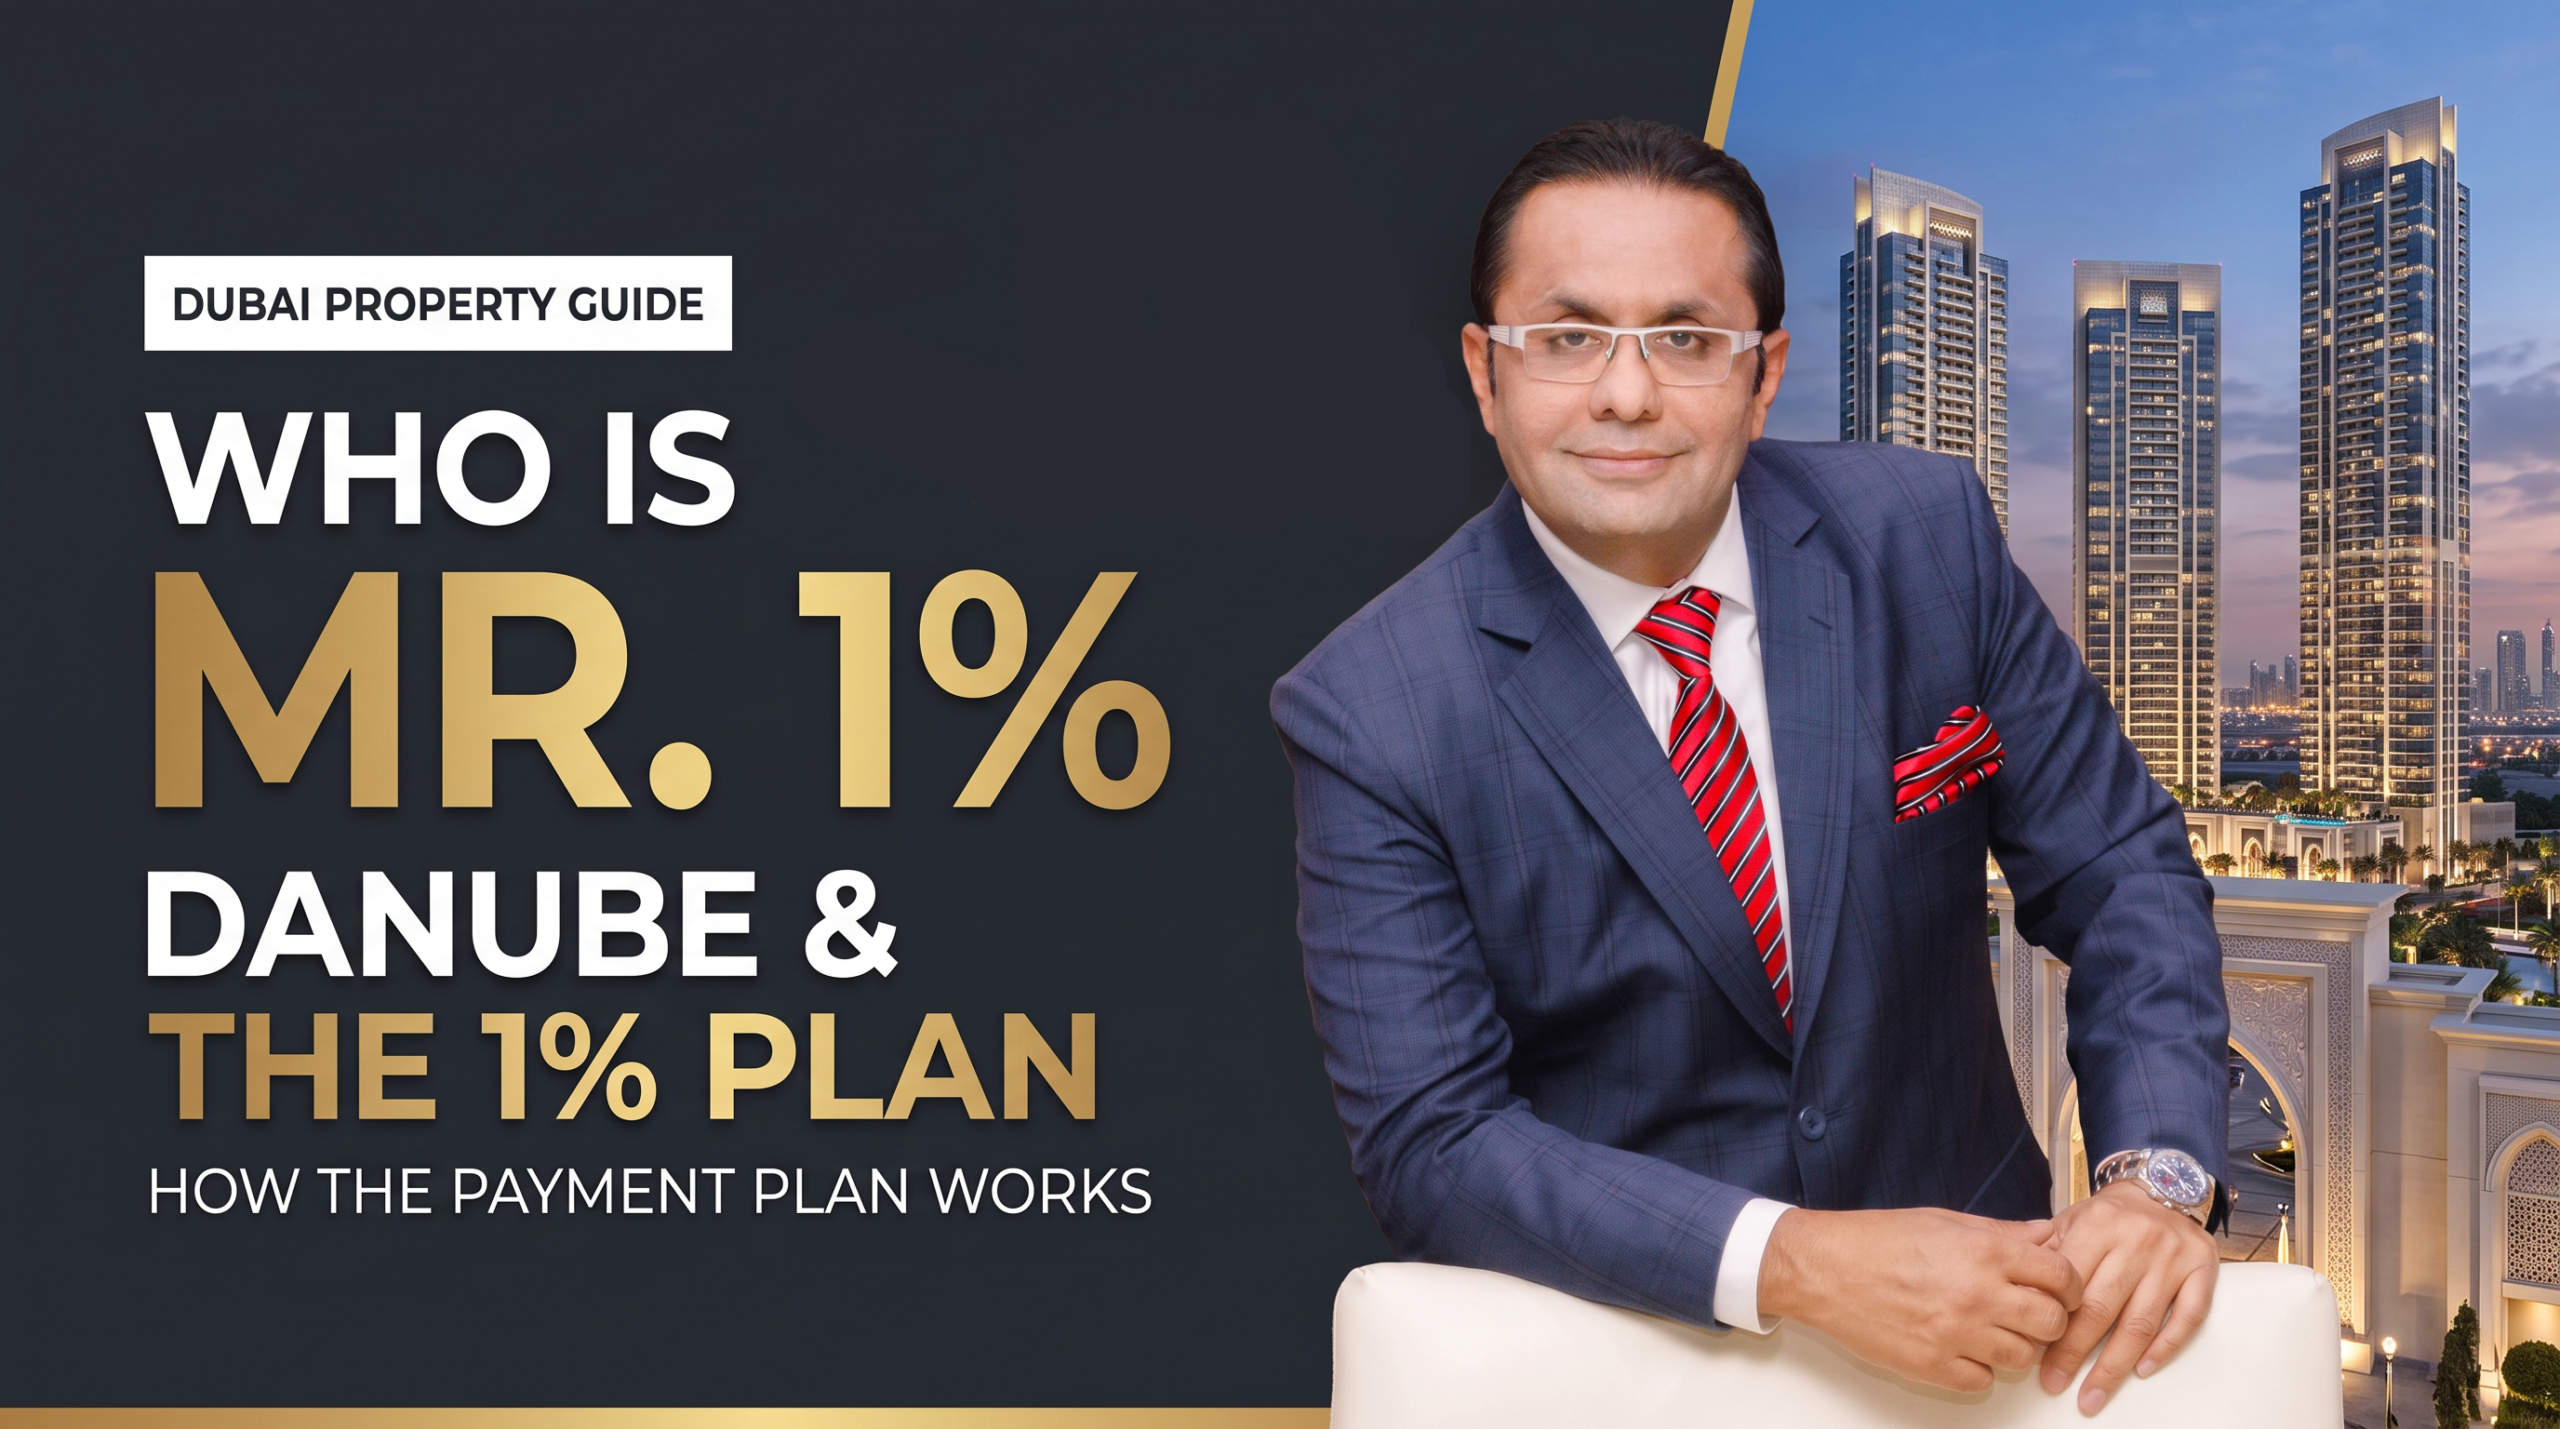

“Mr. 1%” in Dubai refers to Rizwan Sajan, the founder and chairman of Danube Group, whose property business is known for advertising 1% monthly payment plans. The nickname, also expressed as “Dubai’s 1% Man,” connects his public profile with a simple proposition: spread a property purchase across instalments rather than judge it only by the headline price.
The percentage needs one immediate clarification. It refers to a payment calculated on the property’s purchase price not a 1% interest rate, rental return or total deposit. On a home priced at AED 1 million, a 1% instalment is AED 10,000.
Understanding the man behind the nickname is part of the story. Understanding the full payment schedule is what matters when deciding whether a property suits your budget.
Rizwan Sajan and Danube at a Glance
| Question | Answer |
|---|---|
| Who is Rizwan Sajan? | Founder and chairman of Danube Group |
| Why is he called Mr. 1%? | His association with Danube Properties’ 1% monthly payment proposition |
| When was Danube Group established? | 1993 |
| When did its property-development business begin? | 2014 |
| What businesses sit within the group? | Building materials, home furnishings and property development, among others |
| Does every project have the same payment schedule? | No; the applicable offer and purchase documents determine the terms |
Danube Group and Danube Properties are related but distinct parts of the story. The group’s trading roots came first; property development followed more than two decades later.
From Building Materials to Property Development
Sajan’s career began in trading rather than residential development. In his own account, he moved to Kuwait in 1981, aged 18, to work in his uncle’s building-materials business. He has described learning sales, negotiation and customer relationships there before the 1990 invasion disrupted his career and finances.
In a Gulf News interview, Sajan recalled returning to Mumbai and subsequently taking a building-materials brokerage job in Dubai. He later moved into trading on his own account. Danube Group dates its establishment to 1993, starting as a small trading business.
The expansion into home furnishings and, eventually, property development connected several stages of the housing business: supplying materials, fitting out homes and developing places to live.
That background helps explain the breadth of the Danube brand. It does not establish that every project will have lower costs, better construction or stronger investment performance than its neighbours. Those questions still require a project-level assessment.
Danube’s early property business included townhouses
Danube entered property development in 2014. Its early Dreamz development comprised 171 three- and four-bedroom homes; Danube’s reporting identifies its first launch as a townhouse project.
This is a useful distinction when discussing the company’s later expansion. The story is not simply an apartment developer discovering villas for the first time. It is a business broadening its residential formats and the scale of its communities.
Why Is Rizwan Sajan Called the 1% Man?
The nickname links a personal brand to a payment proposition that is easy to remember. A buyer may find a monthly amount easier to relate to income than a seven-figure purchase price.
In a 2024 interview republished by Danube, Sajan discussed marketing as an important part of the group’s growth and described his ambition to turn tenants into homeowners. The 1% message gives that ambition a concrete number.
For a salaried buyer, the appeal is understandable: regular instalments may be easier to plan for than an irregular series of large payments. For a buyer with savings elsewhere, a longer schedule may reduce how much cash must be committed immediately.
However, spreading payments changes their timing. It does not reduce the agreed purchase price or establish that the home is affordable. The deposit, any larger instalments and the amount due at completion remain essential parts of the decision.
The useful question is therefore: Can I meet the entire schedule while covering my other expenses and retaining a reserve?
How Does a 1% Monthly Payment Plan Work?
A developer payment plan sets out how the purchase price is paid over time. It is different from taking a bank mortgage, although a buyer might separately seek financing for part of the purchase, subject to approval.
Read the schedule in four parts:
- Booking and initial payments: What is due when reserving and signing, including charges outside the property price?
- Construction-stage payments: Which instalments are monthly, and are any additional amounts due on specified dates or milestones?
- Completion payment: How much must be paid when the property is ready for handover?
- Post-handover payments: Does the contract expressly allow any balance to continue after possession, and on what terms?
The phrase “1% monthly” does not answer all four questions. Danube’s general payment-plan explanation includes a balance collected when the building is ready, while particular offers may provide different arrangements. Never assume that post-handover instalments are included merely because the advertisement says 1%.
A hypothetical AED 1 million purchase
The following example demonstrates the arithmetic. It is not a current Danube offer, price quotation or promised construction timeline. It assumes a 20% deposit, 45 monthly instalments before handover and 35 afterwards, with no additional payments towards the purchase price.
| Stage | Share of purchase price | Amount |
|---|---|---|
| Initial deposit | 20% | AED 200,000 |
| 45 monthly construction-stage instalments | 45% | AED 10,000 monthly; AED 450,000 total |
| Cumulative property payments at assumed handover | 65% | AED 650,000; subtotal, not an extra charge |
| 35 monthly post-handover instalments | 35% | AED 10,000 monthly; AED 350,000 total |
| Total property price paid | 100% | AED 1,000,000 |
There are 80 monthly instalments after the deposit: six years and eight months, assuming consecutive monthly payments. Possession still depends on completion and the contractual handover conditions, not simply on reaching the illustrated percentage.
Purchase expenses sit outside this table. If the buyer agrees to bear the full 4% registration charge, that adds AED 40,000. DLD’s initial-sale service lists 2% for the seller and 2% for the purchaser; confirm the agreed allocation and any incentive in writing.
On that assumption, the deposit and registration charge alone require AED 240,000. Obtain an itemised statement for administrative charges and budget separately for relevant setup costs. Keep an emergency reserve beyond the money committed to the purchase.
Can Rental Income Cover the Instalments?
Rental income may contribute after the property is ready and available to let. It should not be assumed to cover the remaining payments.
In the example, AED 10,000 monthly equals AED 120,000 annually. Suppose, solely to illustrate the calculation, the apartment produces AED 60,000 in annual gross rent. The owner would still need AED 60,000 from other funds before allowing for service charges, repairs, vacancy or management expenses.
That rent figure is not a forecast or a market benchmark. Its purpose is to show the difference between rental income and the contractual payment obligation.
Timing matters too. Rent may arrive in several payments while instalments fall due monthly. Before completion, buyers may also need to pay for their existing accommodation alongside the developer schedule.
Our guide to property budgeting and the Rule of 3 explains why the cash remaining after a purchase matters as much as the deposit.
Danube’s Expanding Residential Offering
Danube’s portfolio now includes different residential formats. Two examples illustrate why buyers should evaluate the individual development rather than rely on the payment-plan slogan.
- Shahrukhz Residences by Danube: Danube identifies this as a residential development in Dubai Maritime City. Use the complete project name when requesting information so the quotation clearly identifies the intended development.
- Greenz by Danube: A larger community centred on townhouses and villas. Danube has advertised percentage-based monthly payment options for Greenz, including 1%; it should not be described as a blanket exception to the monthly-payment approach.
For either project, request the current schedule for the exact home and offer. A company-wide campaign is not a substitute for unit-specific terms, furnishing specifications or handover conditions.
Guardians Prime’s View: Assess the Property and the Plan Together
A memorable founder and a convenient payment schedule can attract attention. A sound property decision also needs evidence about the home itself.
Compare the total price and what it includes
Compare layout, usable area, condition, location and running costs alongside the purchase price. Where furnishing is included, obtain the written inventory and specification rather than assigning an assumed saving.
If a cash-payment alternative exists, compare its total price with the instalment offer. An offer with no separately charged financing interest can still carry fees and a different overall cost. Do not assume either a financing premium or a discount without quotations.
As our discussion of Dubai property prices explains, broad market figures cannot replace evidence about a particular property. Use relevant completed transactions where available, and account for differences in specification and payment timing.
Check project registration and the recipient of payments
Use DLD’s project-status services or Dubai REST to check the development and its escrow information. Verify payment instructions against the registered project details. DLD’s brokerage guidance directs brokers to ensure off-plan projects are registered and buyers pay property amounts into the relevant escrow account.
Registration and escrow arrangements are important safeguards; they do not establish a guaranteed delivery date or investment return.
Read the terms that matter when circumstances change
Before reserving, establish what happens if you need to sell, miss a payment or face a delay. Review the Sale and Purchase Agreement, or SPA, and ask about:
- Additional instalments and the completion balance.
- Late-payment, default, cancellation and refund provisions.
- Resale conditions, required approvals and associated charges.
- Whether a remaining payment schedule can transfer to another purchaser.
- Accepted payment methods, including arrangements for non-residents.
Do not rely on a future mortgage, a resale or rent beginning immediately at handover to make an otherwise unfunded schedule work.
Frequently Asked Questions
Who is Mr. 1% in Dubai?
The nickname refers to Rizwan Sajan, founder and chairman of Danube Group. It is associated with the 1% monthly property-payment proposition promoted by Danube Properties.
When did Rizwan Sajan establish Danube?
Danube Group was established in 1993 as a trading business. Its property-development business began in 2014, so the group and property division have different starting dates.
Does a 1% payment plan mean 1% interest?
No. It describes an instalment calculated on the purchase price. Whether financing interest or other charges apply depends on the offer and contract; the percentage alone does not establish the total cost.
Does every 1% plan include payments after handover?
No. Check the completion balance and any expressly agreed post-handover schedule. Monthly instalments during construction and instalments after possession are separate features.
Can a non-resident buy using a developer payment plan?
Non-residents can be eligible purchasers, and DLD’s initial-sale registration service provides for their passport documentation. Confirm the property’s ownership eligibility, developer requirements, payment methods and documentation. A developer plan does not automatically approve a separate bank mortgage.
Can I sell before completing all the payments?
Possibly, subject to the applicable contract and transfer requirements. Ask whether the outstanding balance must be settled, whether the plan can transfer, and what approvals or charges apply. Do not assume a future buyer can automatically take over your instalments.
Compare the Full Payment Schedule Before Deciding
Rizwan Sajan’s “Mr. 1%” identity makes a complex purchase easy to discuss. The next step is to turn that headline into a dated budget covering the deposit, instalments, completion payment, ownership costs and cash reserve.
If you are considering a Danube development or comparing off-plan properties in Dubai, contact Guardians Prime Real Estate with your budget and preferred property type. Our team can help you obtain the current developer-issued schedule and compare the home’s price, specification and payment obligations with other suitable options.